A crash compresses a year of legal decisions into an afternoon. You are shaken, the other driver is upset, a tow truck is waiting and someone is already asking you to sign a release. The people who handle claims well are rarely the ones who argue hardest at the roadside. They are the ones who collect facts early, get treatment and avoid saying anything they cannot verify.
This checklist follows the order that matters: safety, evidence, medical care, communication and deadlines. It applies to a typical collision. If someone was seriously hurt or killed, or a commercial vehicle or government employee was involved, call a lawyer before you negotiate anything.
Key facts
- Move to safety, call emergency services and report the crash to police before leaving the scene.
- Photograph vehicles, positions, road conditions, injuries and every document you are given.
- See a doctor promptly; gaps in treatment are used to argue that injuries were minor or unrelated.
- Tell your own insurer the facts, but do not give a recorded statement to the other side without advice.
- Personal injury deadlines vary by state, from one year to six; confirm yours before negotiating.
Minutes after the crash: safety and the police report
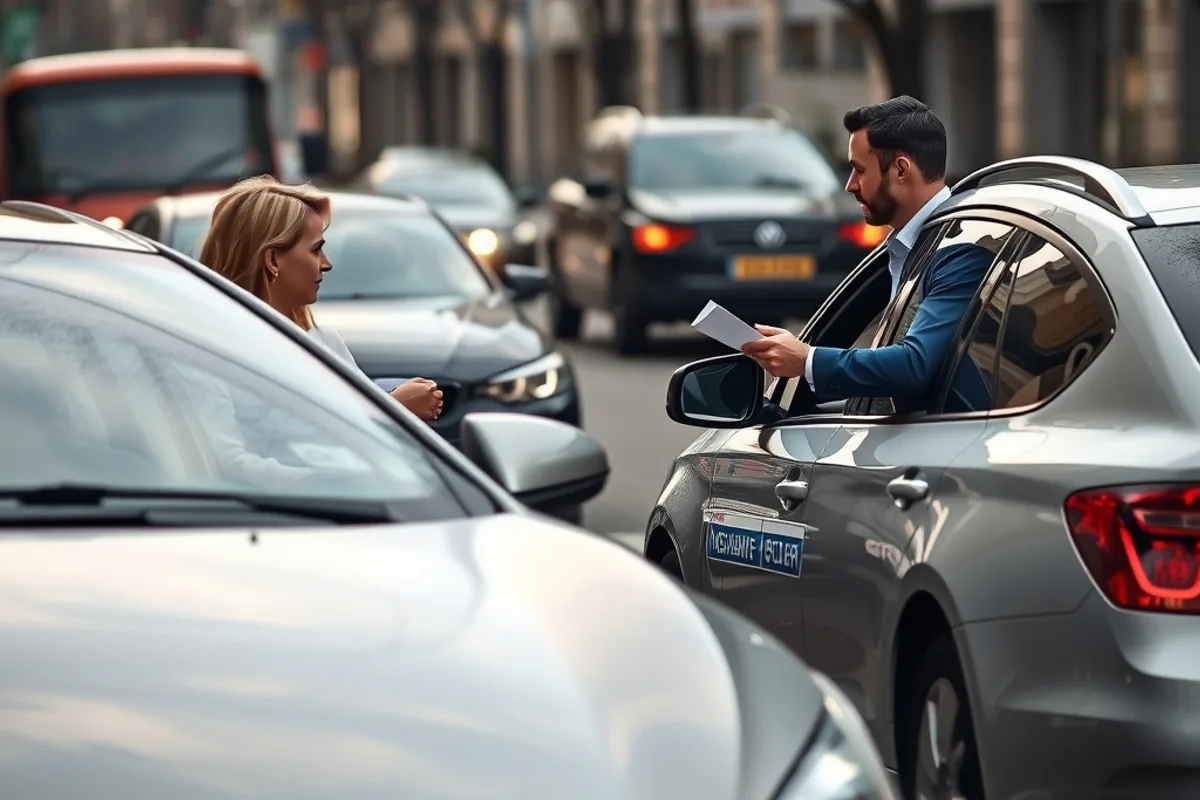
Stop, turn on hazard lights and move vehicles out of traffic if it is safe. Call emergency services if anyone is hurt or the roadway is blocked. Exchange names, insurance details, licence plates and phone numbers with the other driver, and note the number of passengers. Do not discuss who caused the crash, and do not apologise; an apology is not an admission in every state, but it will be quoted in a claim.
Ask the responding officer for the report number and the agency name. In some jurisdictions officers investigate; in others they only take a report. Either way, request a copy as soon as it is available and check it for errors: plate numbers, insurance codes, the stated direction of travel, witness names. A mistake in the report can follow the claim for months.
Document everything before the scene changes
Take wide photographs of the scene before the cars are moved if it is safe, then close-ups of damage, skid marks, debris, signage and traffic signals. Photograph the other driver's insurance card and licence, and every document the officer hands you. If there are witnesses, ask for names and numbers now; people move and memories fade.
Write a timeline the same day: weather, speed, what you saw, what you heard, where the impact occurred and how you felt immediately afterwards. Note any pain, dizziness or confusion even if it seems minor. Keep receipts for towing, a rental car, parking and prescriptions. Put everything in one folder, digital or physical, and stop relying on memory.
Medical care and the paper trail
See a doctor within a day even if you feel fine. Adrenaline masks symptoms, and soft-tissue injuries often peak two or three days later. Tell the clinician exactly what happened and where you felt pain at the scene. Follow the treatment plan, attend referrals and keep every discharge summary, imaging report and prescription.
Insurers read gaps in treatment as evidence that nothing was wrong. That does not mean you should accept unnecessary care. It means continuity matters. If cost or access is a barrier, say so in writing to your insurer and ask for a network provider. Documenting the barrier is better than disappearing from treatment for six weeks.
What to say to insurers, and what not to
Call your own insurer promptly to report the crash and open a claim. Most policies require cooperation, and delay can affect coverage. Give the facts: time, place, vehicles, injuries and the report number. You do not have to speculate about fault, and you should not estimate your injuries or the damage before a professional has looked at them.
The other driver's insurer may call within hours with a friendly adjuster and a request for a recorded statement. You can decline politely and ask that all communication be in writing. Do not sign a release, accept a cheque or agree to a repair estimate before you understand the full extent of the damage. Early offers are often based on the emergency room bill, not on the weeks of recovery that follow.
The strongest claim is built in the first 48 hours, when the evidence is still on the road and the story has not had time to change.
Property damage, rentals and total losses
Get two repair estimates and photographs of the damage. Your insurer may direct you to a network shop; you generally retain the right to choose a repairer, but the insurer is only obligated to pay the reasonable market cost. Ask for the estimate in writing and check whether it includes hidden damage discovered after panels are removed.
If the car is declared a total loss, the settlement should reflect the actual cash value of a comparable vehicle in your market, not the original purchase price or the outstanding loan. Gather listings, maintenance records and any recent upgrades. Ask how the valuation was produced and whether you can submit comparable sales. Rental reimbursement depends on your policy limits, so confirm the daily cap and the number of days before you accept a long repair.
When a lawyer pays for themselves
Personal injury lawyers usually work on contingency, so there is no upfront fee. That does not mean every fender-bender needs counsel. A claim that is clearly the other driver's fault, with minor damage and a short recovery, can often be settled directly. A lawyer becomes valuable when liability is disputed, the injuries are serious or permanent, a commercial or government vehicle is involved, or the insurer is using delay as a tactic.
Interview more than one lawyer and ask what percentage they take, whether costs are deducted before or after the fee, who advances expenses and what happens if the case loses. Get the contingency agreement in writing. Be wary of anyone who guarantees a number before reviewing the medical records.
Deadlines, settlements and closing the claim
The statute of limitations for personal injury varies by state, commonly between two and three years but sometimes as short as one and as long as six. Claims against a government entity can require a formal notice within 60 to 180 days. Property damage and contract claims may have different periods. Confirm the deadline for your jurisdiction and put it on a calendar.
Do not settle until treatment is finished or a doctor has given a final prognosis. A release is final: signing it ends the claim, including for complications you did not anticipate. Read the settlement statement line by line, including medical liens, attorney costs and any unpaid providers. Keep copies of the release, the cheque and the closing letter. If something feels rushed, ask for a day to review it; a legitimate offer will survive one more day.
This article is general information, not legal advice. Accident rules and deadlines differ by state, and a local lawyer can tell you which ones apply to your claim.
Official source: NHTSA — traffic safety and crash reporting. This article is general information, not legal advice.